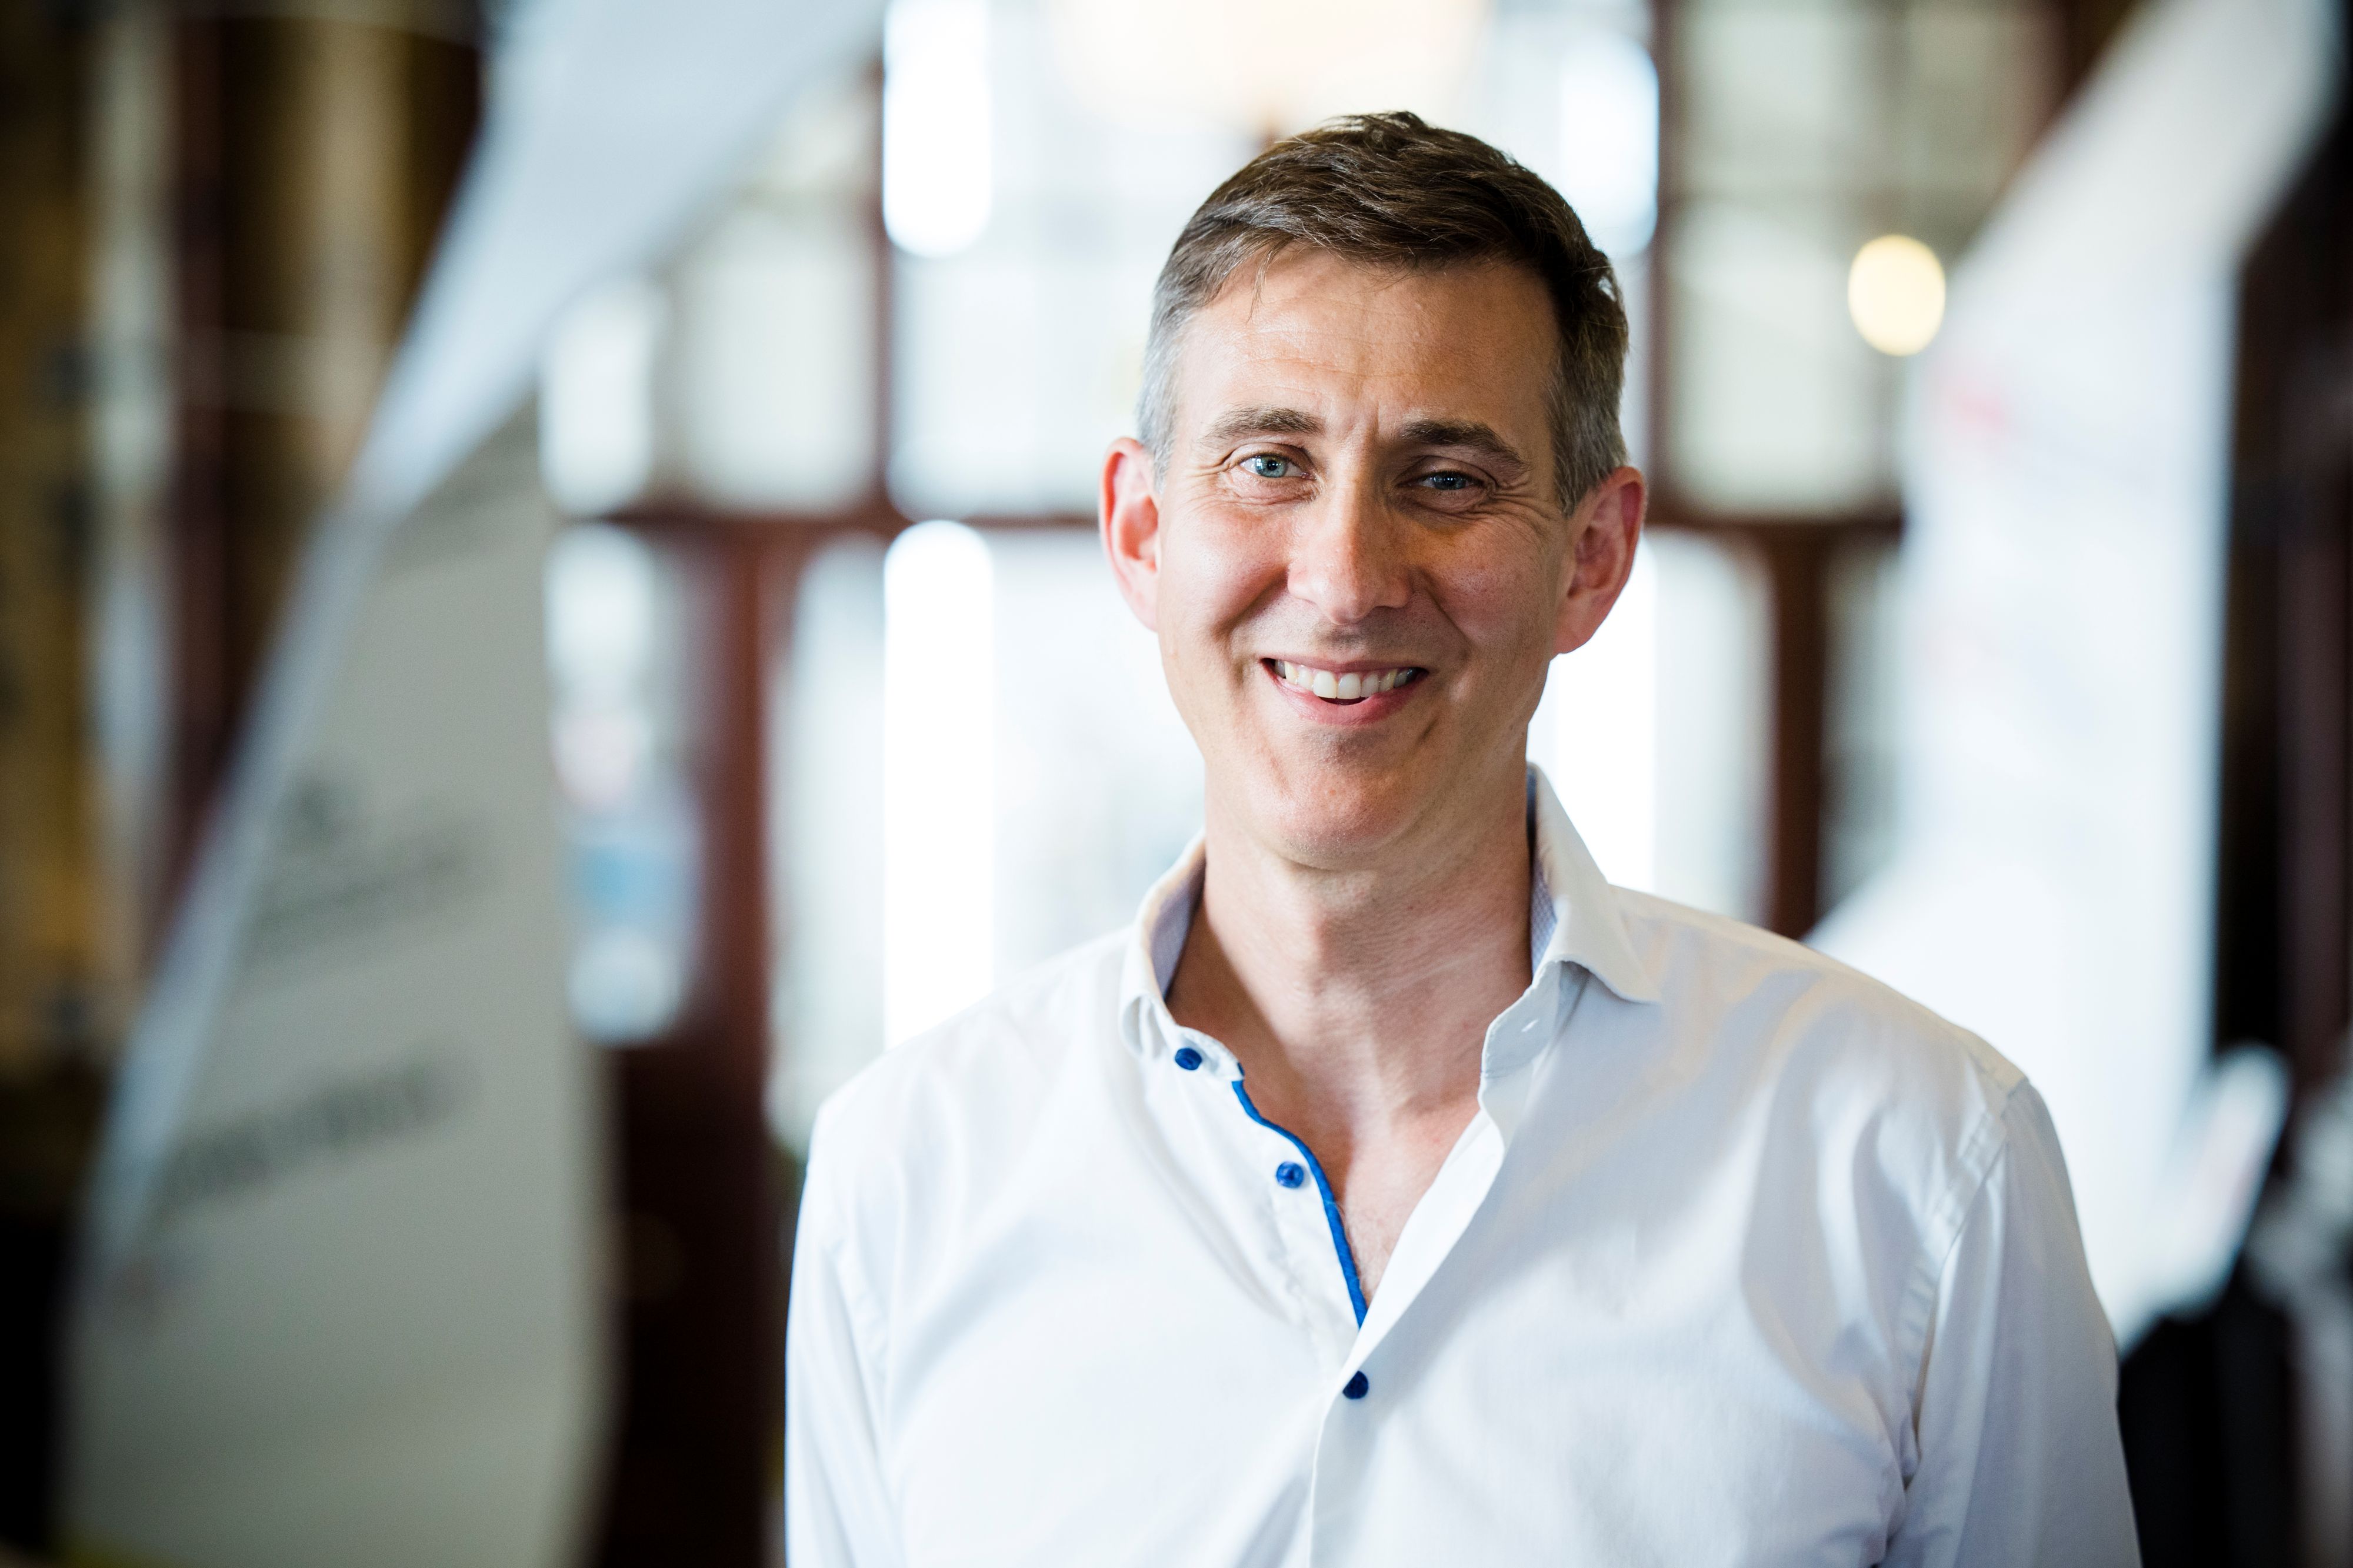
Ahead of Carbon Unbound Europe, we interviewed Chris Sherwood, Secretary-General of the Negative Emissions Platform (NEP) to unpack what it will take to scale permanent carbon removal across the continent. From bridging the price gap to integrating permanent CDR into the EU ETS, here’s what he had to say.
Why is integrating permanent carbon removals into the EU ETS so important?
Integrating permanent carbon removals into the EU ETS would create the most significant legislative demand signal for permanent CDR globally. The EU’s proposed commitment to purchase 250 million tonnes of permanent carbon removals by 2040 sends a powerful signal that Europe intends to build a market for high-quality carbon removals and reinforce its leadership in this emerging industry.
What would it take to make the EU’s 250 million tonne target a reality?
There are three fundamental requirements: closing the cost gap, creating confidence that the necessary supply will be developed, and ensuring that the EU supports a broad portfolio of CDR technologies.
First, the EU needs to address the gap between the cost of producing permanent carbon removals and the price of EU allowances. In its legislative proposal, the European Commission has allocated 10 million allowances from within the cap to address the price gap. However, NEP’s preliminary analysis suggests there will still be a price gap of EUR 16-19.6 billion. Without closing the price gap, the EU risks not being able to purchase 250 Mt of permanent CDR.
Second, the Commission needs to provide sufficient certainty for developers to invest in new projects. Long-term offtake agreements will be particularly important, as they can provide the revenue certainty needed to secure project financing and make large-scale investment decisions.
Lastly, the EU also needs to ensure that the framework remains technology-open, so that the market can draw on the full portfolio of high-quality permanent CDR approaches as they mature.
How can the EU help close the gap between the cost of CDR and the price of EU allowances?
There are several complementary measures the EU could take.
- Earmark additional allowances within the ETS cap. The proposed 250 million tonnes should be backed by sufficient allowances, with the 2034 review assessing whether additional allowances are needed as the market develops.
- Make permanent CDR eligible under both phases of the Industrial Decarbonisation Bank, including through Carbon Contracts for Difference to provide longer-term revenue certainty.
- Make effective use of Member State ETS revenues. Member States should be encouraged to direct a meaningful share of ETS revenues towards developing permanent CDR and the infrastructure needed to deploy it.
- Allow some direct integration. Giving ETS operators the option to purchase or generate certified permanent CDR directly can create an additional source of demand.
No single instrument is likely to close the gap on its own. The EU should therefore build a complementary package of demand-side and investment-support measures.
What role can long-term offtake agreements play in growing the CDR market?
Long-term offtake agreements provide developers with greater certainty over future revenues, which is critical when projects require substantial upfront capital investment. For the ETS, purchasing needs to start early enough for projects to be developed and financed. Offtake agreements should therefore be signed no later than 2029 to ensure supply of permanent CDR from 2031. They should also provide meaningful long-term certainty, and therefore should have a minimum duration of eight years to give projects sufficient visibility to underpin investment.
Finally, the Commission needs to provide some visibility beyond 2040. If the market sees a hard stop in 2040, it becomes much harder for companies to make the investments needed today. A credible pathway beyond 2040 would therefore significantly strengthen the signal created by the ETS.
What should policymakers prioritise to give investors greater confidence in the market?
Beyond the compliance market, policymakers can provide more certainty for buyers and investors to engage with permanent CDR through the Voluntary Carbon Market. The Commission’s intention to come forward with Guidance on Use Cases could go a long way here to provide the confidence for companies buying carbon removal credits to communicate them.
How can the EU scale permanent carbon removal while maintaining high standards for environmental integrity?
The EU should continue to make the CRCF a robust standard for what constitutes a high-quality carbon removal. Where there are uncertainties, methodologies should take a conservative approach, including through appropriate uncertainty factors. At the same time, methodologies need to evolve as scientific understanding and monitoring capabilities improve. The framework should therefore be regularly updated to reflect the latest scientific evidence.
Where a particular use case requires additional safeguards beyond the CRCF, those requirements should be clearly defined, rather than introduced through technology-specific restrictions. In the context of the ETS, if policy makers believe additional criteria are needed beyond the CRCF, this should be transparently set out in a Delegated Act.
What do you think is currently missing from the EU’s approach to permanent carbon removal?
The ETS is an important piece of the puzzle, but it cannot be the whole CDR strategy.
First, the EU needs to consider how permanent CDR is reflected in national climate targets. The forthcoming legislative proposal expected in Q4 2026 is an important opportunity to establish a clear role for permanent removals within national targets, alongside emissions reductions and temporary CDR. This proposal will be essential to ensure a geographical balance across Europe so that all Member States are able to build and benefit from their own permanent CDR sector.
Second, infrastructure is a major missing piece. Many potential users of permanent CDR are reluctant to enter into long-term commitments because of uncertainty around projects and the limited availability of the infrastructure needed to transport and store CO₂. Developing this infrastructure will be essential to enable both supply and demand to scale.
Looking ahead, what would success look like for permanent CDR in the EU ETS?
Success would ultimately mean the EU reaching the proposed 250 million tonne target with high-quality, permanent carbon removals.
But there are three elements that would make that success durable.
First, the framework should remain technology-open, with clear and objective criteria explaining how additional permanent CDR methods can become eligible as methodologies are developed and certified.
Second, the EU needs to create the conditions for a competitive European CDR industry, including long-term demand, investment certainty and the infrastructure needed to deploy projects at scale.
And third, there needs to be a clear pathway beyond 2040. The 250 million tonne target should be seen as a foundation for a long-term market, not an endpoint. If Europe wants to maintain its leadership in permanent carbon removal, investors and project developers need visibility on what comes next.
What role does NEP play in helping its Members navigate the fast-moving CDR market?
We help our Members understand what policy developments mean for their businesses and give them a direct role in shaping our advocacy. That means going beyond reporting on a legislative proposal to explaining its implications for project development, financing and demand.
Through our working groups and regular exchanges, Members bring practical experience into our discussions with policymakers. A developer’s financing challenge or a buyer’s uncertainty over claims can reveal where a proposed framework needs to change. Our role is to turn that experience into concrete recommendations and make sure the diversity of the permanent CDR sector is represented.
What do companies gain from being part of the NEP community?
By being part of the Negative Emissions Platform, companies gain access to policy expertise, a collective voice and relationships across the permanent carbon removal market. Our community brings together developers, suppliers, buyers, marketplaces and investors, giving Members opportunities to understand each other’s needs and identify potential partners.
Members can help shape our policy positions, contribute evidence to our advocacy and raise issues that might otherwise be overlooked. They also have opportunities to share their work through our communications, events and engagement with policymakers.
For a growing company, membership means having a team in Brussels working on the conditions its business needs to succeed, alongside peers facing many of the same challenges.
Beyond policy, what are the biggest challenges you’re hearing from your members right now?
Securing long-term buyers and financing remains a major challenge, particularly for methods whose place in EU policy is still uncertain. Buyer interest does not always translate into the contracts developers need to finance and build projects.
Members are also looking at how CDR can fit into existing industries and where projects can develop across Europe. Access to energy, feedstocks and industrial partners will shape which regions benefit.
For methods that need CO₂ transport and storage, the questions are practical: when will infrastructure be ready, how can projects connect, and what will it cost? The CO₂ transport package expected next year needs to help answer those questions.
What makes NEP different from other trade organisations supporting the CDR industry?
What sets NEP apart is the EU focus that we have and the role Members play in shaping our advocacy. Every Member, regardless of size, can put forward a proposal, debate it with peers and make their case directly to the Secretariat. Those discussions shape the positions we take to policymakers. For a smaller company, that means a seat at the table and the opportunity to influence decisions that will affect its future.
We represent permanent carbon removal across different methods and bring developers, buyers and investors into the same discussions. We work through differences to build positions that Members can stand behind, grounded in the realities of developing projects, financing them and buying removals.
We take that collective expertise directly into our EU advocacy, which is what we specialise in. Alongside this, we help build the sector’s presence in international climate discussions. As a UNFCCC Observer, we helped bring the community together around the first dedicated CDR Pavilion at COP30 and are hosting Think Negative at COP31. Joining NEP means helping shape our priorities and having a team working to translate them into concrete policy proposals.
In Partnership with Negative Emissions Platform
Thank you Negative Emissions Platform, our official Buyers Workshop partner, for providing these policy and market insights. To take a deeper dive into the carbon removal landscape and meet the NEP team in person, discover more about Carbon Unbound Europe.
Ahead of Carbon Unbound Europe, we interviewed Chris Sherwood, Secretary-General of the Negative Emissions Platform (NEP) to unpack what it will take to scale permanent carbon removal across the continent. From bridging the price gap to integrating permanent CDR into the EU ETS, here’s what he had to say.
Why is integrating permanent carbon removals into the EU ETS so important?
Integrating permanent carbon removals into the EU ETS would create the most significant legislative demand signal for permanent CDR globally. The EU’s proposed commitment to purchase 250 million tonnes of permanent carbon removals by 2040 sends a powerful signal that Europe intends to build a market for high-quality carbon removals and reinforce its leadership in this emerging industry.
What would it take to make the EU’s 250 million tonne target a reality?
There are three fundamental requirements: closing the cost gap, creating confidence that the necessary supply will be developed, and ensuring that the EU supports a broad portfolio of CDR technologies.
First, the EU needs to address the gap between the cost of producing permanent carbon removals and the price of EU allowances. In its legislative proposal, the European Commission has allocated 10 million allowances from within the cap to address the price gap. However, NEP’s preliminary analysis suggests there will still be a price gap of EUR 16-19.6 billion. Without closing the price gap, the EU risks not being able to purchase 250 Mt of permanent CDR.
Second, the Commission needs to provide sufficient certainty for developers to invest in new projects. Long-term offtake agreements will be particularly important, as they can provide the revenue certainty needed to secure project financing and make large-scale investment decisions.
Lastly, the EU also needs to ensure that the framework remains technology-open, so that the market can draw on the full portfolio of high-quality permanent CDR approaches as they mature.
How can the EU help close the gap between the cost of CDR and the price of EU allowances?
There are several complementary measures the EU could take.
- Earmark additional allowances within the ETS cap. The proposed 250 million tonnes should be backed by sufficient allowances, with the 2034 review assessing whether additional allowances are needed as the market develops.
- Make permanent CDR eligible under both phases of the Industrial Decarbonisation Bank, including through Carbon Contracts for Difference to provide longer-term revenue certainty.
- Make effective use of Member State ETS revenues. Member States should be encouraged to direct a meaningful share of ETS revenues towards developing permanent CDR and the infrastructure needed to deploy it.
- Allow some direct integration. Giving ETS operators the option to purchase or generate certified permanent CDR directly can create an additional source of demand.
No single instrument is likely to close the gap on its own. The EU should therefore build a complementary package of demand-side and investment-support measures.
What role can long-term offtake agreements play in growing the CDR market?
Long-term offtake agreements provide developers with greater certainty over future revenues, which is critical when projects require substantial upfront capital investment. For the ETS, purchasing needs to start early enough for projects to be developed and financed. Offtake agreements should therefore be signed no later than 2029 to ensure supply of permanent CDR from 2031. They should also provide meaningful long-term certainty, and therefore should have a minimum duration of eight years to give projects sufficient visibility to underpin investment.
Finally, the Commission needs to provide some visibility beyond 2040. If the market sees a hard stop in 2040, it becomes much harder for companies to make the investments needed today. A credible pathway beyond 2040 would therefore significantly strengthen the signal created by the ETS.
What should policymakers prioritise to give investors greater confidence in the market?
Beyond the compliance market, policymakers can provide more certainty for buyers and investors to engage with permanent CDR through the Voluntary Carbon Market. The Commission’s intention to come forward with Guidance on Use Cases could go a long way here to provide the confidence for companies buying carbon removal credits to communicate them.
How can the EU scale permanent carbon removal while maintaining high standards for environmental integrity?
The EU should continue to make the CRCF a robust standard for what constitutes a high-quality carbon removal. Where there are uncertainties, methodologies should take a conservative approach, including through appropriate uncertainty factors. At the same time, methodologies need to evolve as scientific understanding and monitoring capabilities improve. The framework should therefore be regularly updated to reflect the latest scientific evidence.
Where a particular use case requires additional safeguards beyond the CRCF, those requirements should be clearly defined, rather than introduced through technology-specific restrictions. In the context of the ETS, if policy makers believe additional criteria are needed beyond the CRCF, this should be transparently set out in a Delegated Act.
What do you think is currently missing from the EU’s approach to permanent carbon removal?
The ETS is an important piece of the puzzle, but it cannot be the whole CDR strategy.
First, the EU needs to consider how permanent CDR is reflected in national climate targets. The forthcoming legislative proposal expected in Q4 2026 is an important opportunity to establish a clear role for permanent removals within national targets, alongside emissions reductions and temporary CDR. This proposal will be essential to ensure a geographical balance across Europe so that all Member States are able to build and benefit from their own permanent CDR sector.
Second, infrastructure is a major missing piece. Many potential users of permanent CDR are reluctant to enter into long-term commitments because of uncertainty around projects and the limited availability of the infrastructure needed to transport and store CO₂. Developing this infrastructure will be essential to enable both supply and demand to scale.
Looking ahead, what would success look like for permanent CDR in the EU ETS?
Success would ultimately mean the EU reaching the proposed 250 million tonne target with high-quality, permanent carbon removals.
But there are three elements that would make that success durable.
First, the framework should remain technology-open, with clear and objective criteria explaining how additional permanent CDR methods can become eligible as methodologies are developed and certified.
Second, the EU needs to create the conditions for a competitive European CDR industry, including long-term demand, investment certainty and the infrastructure needed to deploy projects at scale.
And third, there needs to be a clear pathway beyond 2040. The 250 million tonne target should be seen as a foundation for a long-term market, not an endpoint. If Europe wants to maintain its leadership in permanent carbon removal, investors and project developers need visibility on what comes next.
What role does NEP play in helping its Members navigate the fast-moving CDR market?
We help our Members understand what policy developments mean for their businesses and give them a direct role in shaping our advocacy. That means going beyond reporting on a legislative proposal to explaining its implications for project development, financing and demand.
Through our working groups and regular exchanges, Members bring practical experience into our discussions with policymakers. A developer’s financing challenge or a buyer’s uncertainty over claims can reveal where a proposed framework needs to change. Our role is to turn that experience into concrete recommendations and make sure the diversity of the permanent CDR sector is represented.
What do companies gain from being part of the NEP community?
By being part of the Negative Emissions Platform, companies gain access to policy expertise, a collective voice and relationships across the permanent carbon removal market. Our community brings together developers, suppliers, buyers, marketplaces and investors, giving Members opportunities to understand each other’s needs and identify potential partners.
Members can help shape our policy positions, contribute evidence to our advocacy and raise issues that might otherwise be overlooked. They also have opportunities to share their work through our communications, events and engagement with policymakers.
For a growing company, membership means having a team in Brussels working on the conditions its business needs to succeed, alongside peers facing many of the same challenges.
Beyond policy, what are the biggest challenges you’re hearing from your members right now?
Securing long-term buyers and financing remains a major challenge, particularly for methods whose place in EU policy is still uncertain. Buyer interest does not always translate into the contracts developers need to finance and build projects.
Members are also looking at how CDR can fit into existing industries and where projects can develop across Europe. Access to energy, feedstocks and industrial partners will shape which regions benefit.
For methods that need CO₂ transport and storage, the questions are practical: when will infrastructure be ready, how can projects connect, and what will it cost? The CO₂ transport package expected next year needs to help answer those questions.
What makes NEP different from other trade organisations supporting the CDR industry?
What sets NEP apart is the EU focus that we have and the role Members play in shaping our advocacy. Every Member, regardless of size, can put forward a proposal, debate it with peers and make their case directly to the Secretariat. Those discussions shape the positions we take to policymakers. For a smaller company, that means a seat at the table and the opportunity to influence decisions that will affect its future.
We represent permanent carbon removal across different methods and bring developers, buyers and investors into the same discussions. We work through differences to build positions that Members can stand behind, grounded in the realities of developing projects, financing them and buying removals.
We take that collective expertise directly into our EU advocacy, which is what we specialise in. Alongside this, we help build the sector’s presence in international climate discussions. As a UNFCCC Observer, we helped bring the community together around the first dedicated CDR Pavilion at COP30 and are hosting Think Negative at COP31. Joining NEP means helping shape our priorities and having a team working to translate them into concrete policy proposals.
In Partnership with Negative Emissions Platform
Thank you Negative Emissions Platform, our official Buyers Workshop partner, for providing these policy and market insights. To take a deeper dive into the carbon removal landscape and meet the NEP team in person, discover more about Carbon Unbound Europe.